
A secured business loan requires four categories of documents: KYC proof of the applicant, business registration proof, financial statements (ITRs, bank statements, GST returns), and collateral papers for whatever asset is pledged. Missing or mismatched paperwork — not weak eligibility — is the single biggest reason approvals get delayed.
This matters most for small business owners, traders, and self-employed professionals in cities like Mumbai, where a large share of secured loans are taken against residential or commercial property, and where a single unclear title document can stall a file for weeks. The checklist below covers exactly what lenders ask for, in the order they usually ask for it.
A secured business loan is one where the borrower pledges an asset — typically property, but sometimes equipment, inventory, or securities — as collateral. In exchange, lenders offer lower interest rates, higher loan amounts, and longer repayment tenures than unsecured loans, since their risk is backed by something they can recover value from if repayment stops. Most lenders require collateral once the loan amount crosses a certain threshold, commonly above ₹75 lakh, though this varies by lender.
The trade-off is documentation. Because collateral is involved, a secured loan file needs everything an unsecured loan needs, plus a full legal paper trail for the asset itself.
Every application starts with verifying who is borrowing. Lenders typically ask for:
If even one director’s KYC is incomplete, the entire file can get held up — so this is worth clearing first, not last.
Lenders need evidence the business is legally registered and has been operating long enough to be creditworthy. Most lenders look for a minimum business vintage of 1–3 years. Typical documents include:
This is where consistency matters more than volume. Lenders cross-check every figure across every document, so a mismatch between your ITR and your bank statement raises questions even when the business is genuinely healthy. Expect to provide:
A CIBIL score of 650–750 or higher is commonly expected alongside these documents, though the exact threshold varies by lender and loan size.
The collateral file is the part most applicants underestimate — and the part where legal drafting support genuinely changes outcomes.
If the collateral is property (residential, commercial, or industrial):
If the collateral is equipment, machinery, or inventory:
If the collateral is securities or fixed deposits:
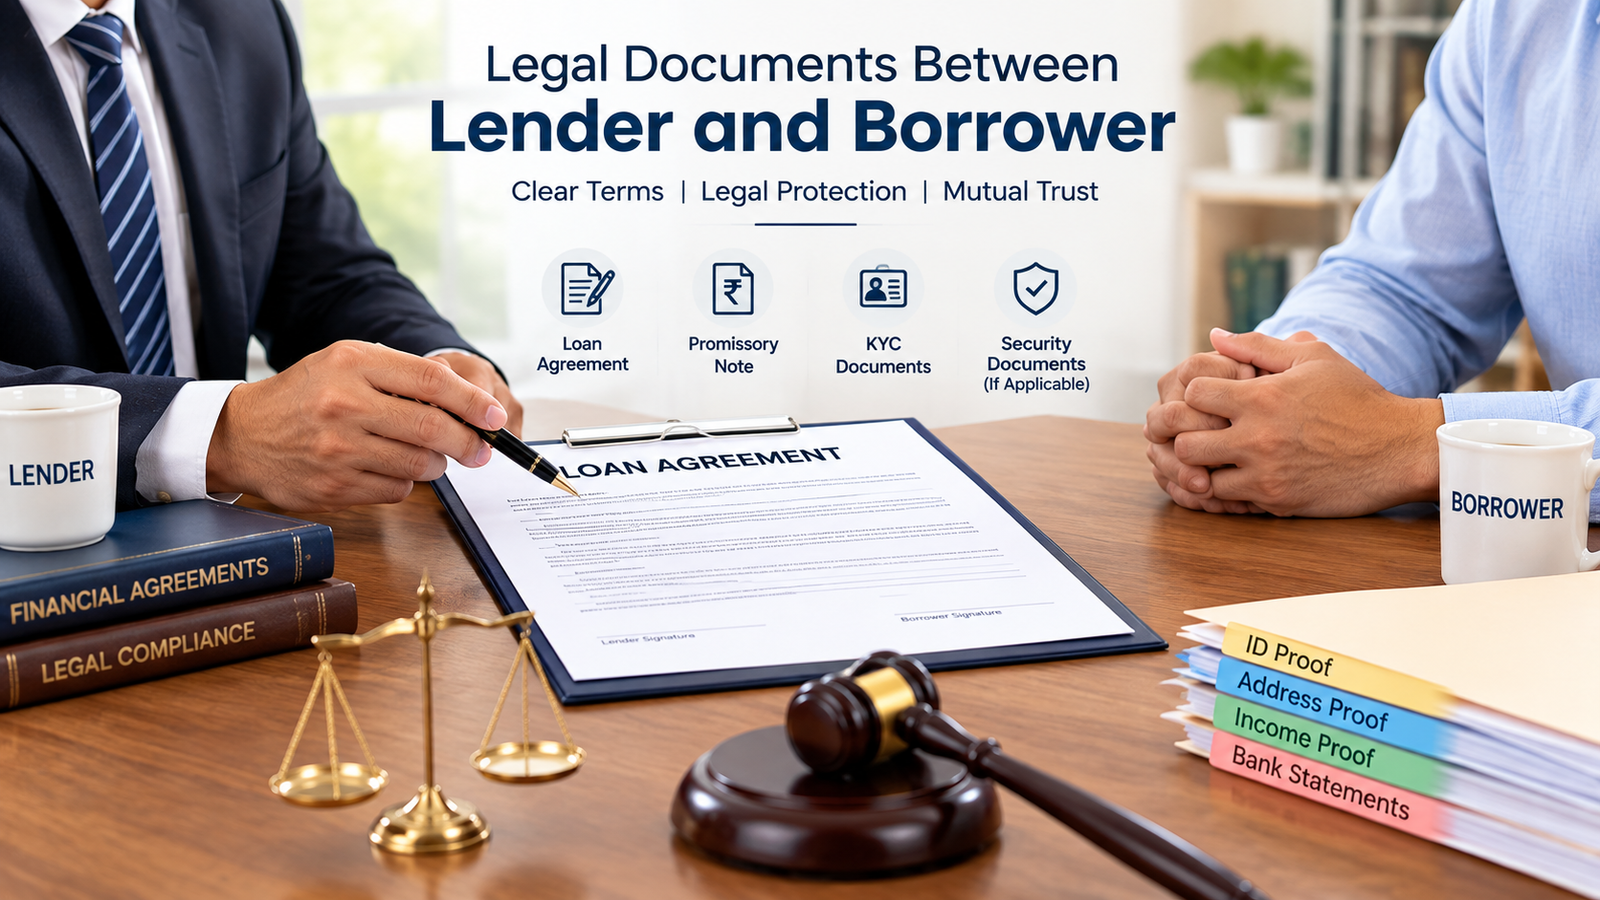
Once the lender has reviewed everything above, a final round of paperwork closes the loop:
Based in Mumbai, Draft My Documents works with business owners across India on exactly the documents that hold up a secured loan file — property search reports, title verification, and the mortgage or loan agreements that need to be legally airtight before a lender will sign off. Most delays we see aren’t about eligibility; they’re about a property document that doesn’t match the applicant’s name, a missing encumbrance certificate, or a loan agreement drafted without proper review. Getting these right before submission, rather than after a lender flags them, is what actually shortens approval time.
Related reading: Benefits of Taking a Loan Against Residential Property and Why a Property Search Report Should Come Before Every Purchase.
RBI or industry report on average secured business loan approval timelines in India
Most lenders require a minimum of 1–3 years of operating history, though some NBFCs offer relaxed norms for newer businesses with strong financials.
Lenders commonly look for a CIBIL score of 650–750 or above, though secured loans are generally more forgiving than unsecured ones since collateral reduces the lender’s risk.
Yes. A sale deed shows ownership at the time of purchase, but a property search report verifies there’s no dispute, lien, or encumbrance since then — lenders specifically ask for this before accepting property as collateral.
Basic KYC and financial documents remain largely the same, though NBFCs sometimes apply slightly relaxed eligibility norms compared to banks.
Timelines vary by lender, but a complete, consistent document file is the single biggest factor in speeding up approval — incomplete or mismatched paperwork is the most common cause of delay.
A secured business loan only moves as fast as its weakest document. If you want your property papers, search report, and loan agreement reviewed and prepared properly before you apply, Get In Touch With Draft My Documents for a free consultation.


WhatsApp us