
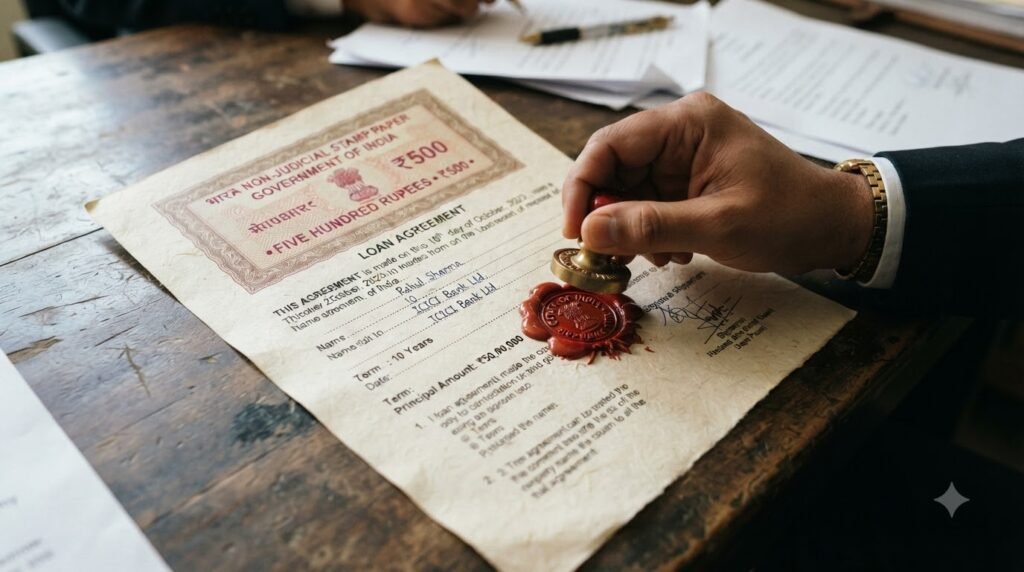
A private loan — money lent between individuals, friends, or family — needs a written, signed, and properly stamped loan agreement to be legally enforceable in India. Without one, recovering the money through a court becomes far harder, and cash loans above ₹20,000 can also trigger tax penalties under Section 269SS of the Income Tax Act.
This matters more than most lenders realise in cities like Mumbai, where private lending between relatives, business partners, and close contacts is common — and where an unstamped or verbally agreed loan is often the reason a dispute goes nowhere in court. Here’s exactly what the paperwork should cover.
Private loans feel informal because the relationship is informal. Legally, that changes nothing. Under the Indian Contract Act, 1872, a loan is a contract, and like any contract it needs offer, acceptance, consideration, and lawful terms to be enforceable — none of which a verbal understanding or a bank transfer with no accompanying document can reliably prove.
Two other legal realities make documentation non-negotiable rather than optional:
A private loan agreement doesn’t need to be long, but it does need to be complete. At minimum, it should cover:
A loan without an acceleration clause forces the lender to sue separately for each missed instalment as it falls due — which is one reason so many private loans in India are never actually enforced when a borrower stops paying.
An unstamped loan agreement is inadmissible as evidence the moment you actually need it — meaning if the borrower stops paying and the matter goes to court, an unstamped document can’t be relied on to prove the loan even happened. Stamp duty for loan agreements is governed by the respective state’s Stamp Act, so the exact value depends on where the agreement is executed. Registration isn’t mandatory for most personal loan agreements, but proper stamping is what makes the document usable if a dispute ever arises.
These two documents are often confused, but they aren’t interchangeable:
For loans involving meaningful amounts, family property, or a business relationship, a full loan agreement is worth the extra page.
Yes. A properly drafted, signed, and stamped loan agreement is enforceable under the Indian Contract Act, 1872, regardless of the personal relationship between lender and borrower.
Registration is not mandatory for most personal loan agreements, but proper stamp duty payment is essential — an unstamped agreement can be ruled inadmissible in court.
Beyond the enforceability risk, cash loans above ₹20,000 can attract a penalty under Section 269SS of the Income Tax Act — such amounts should be transferred through a bank account and backed by a written agreement.
A promissory note works for small, simple, short-term loans, but a full loan agreement is safer for larger amounts, secured loans, or anything with interest and a repayment schedule.
The most common reasons are an unstamped document, no written agreement at all, vague repayment terms, or a security clause that was never backed by an actual mortgage or charge document.
Based in Mumbai, Draft My Documents drafts and reviews private loan agreements, promissory notes, and related affidavits for individuals and businesses across India. We make sure the agreement is properly stamped for the relevant state, includes an enforceable default and acceleration clause, and — where the loan is secured against property — that the security is actually created through the right legal document, not just mentioned in a line of text.
Related reading: Affidavit and Indemnity Bond Drafting and Property Agreement Drafting.
A private loan is only as safe as the paperwork behind it. If you’re lending or borrowing a meaningful amount, Get In Touch With Draft My Documents for a properly drafted, correctly stamped loan agreement.
WhatsApp us